Chicago’s Ferrous Scrap Market
Chicago’s ferrous scrap market could see continued upward momentum in November, with current market indicators pointing toward another potential price increase across all grades. Following October’s $30/GT increase, which marked the first upward movement in prime scrap since February 2026, conditions appear favorable heading into the final two months of the year.
Full mill order books, tightening scrap supply, and Busheling futures trading above $500/GT are all contributing to a stronger market outlook. With most scheduled mill outages expected to conclude heading into November, increased production activity and renewed mill purchasing could create additional upward pressure during the monthly trade.
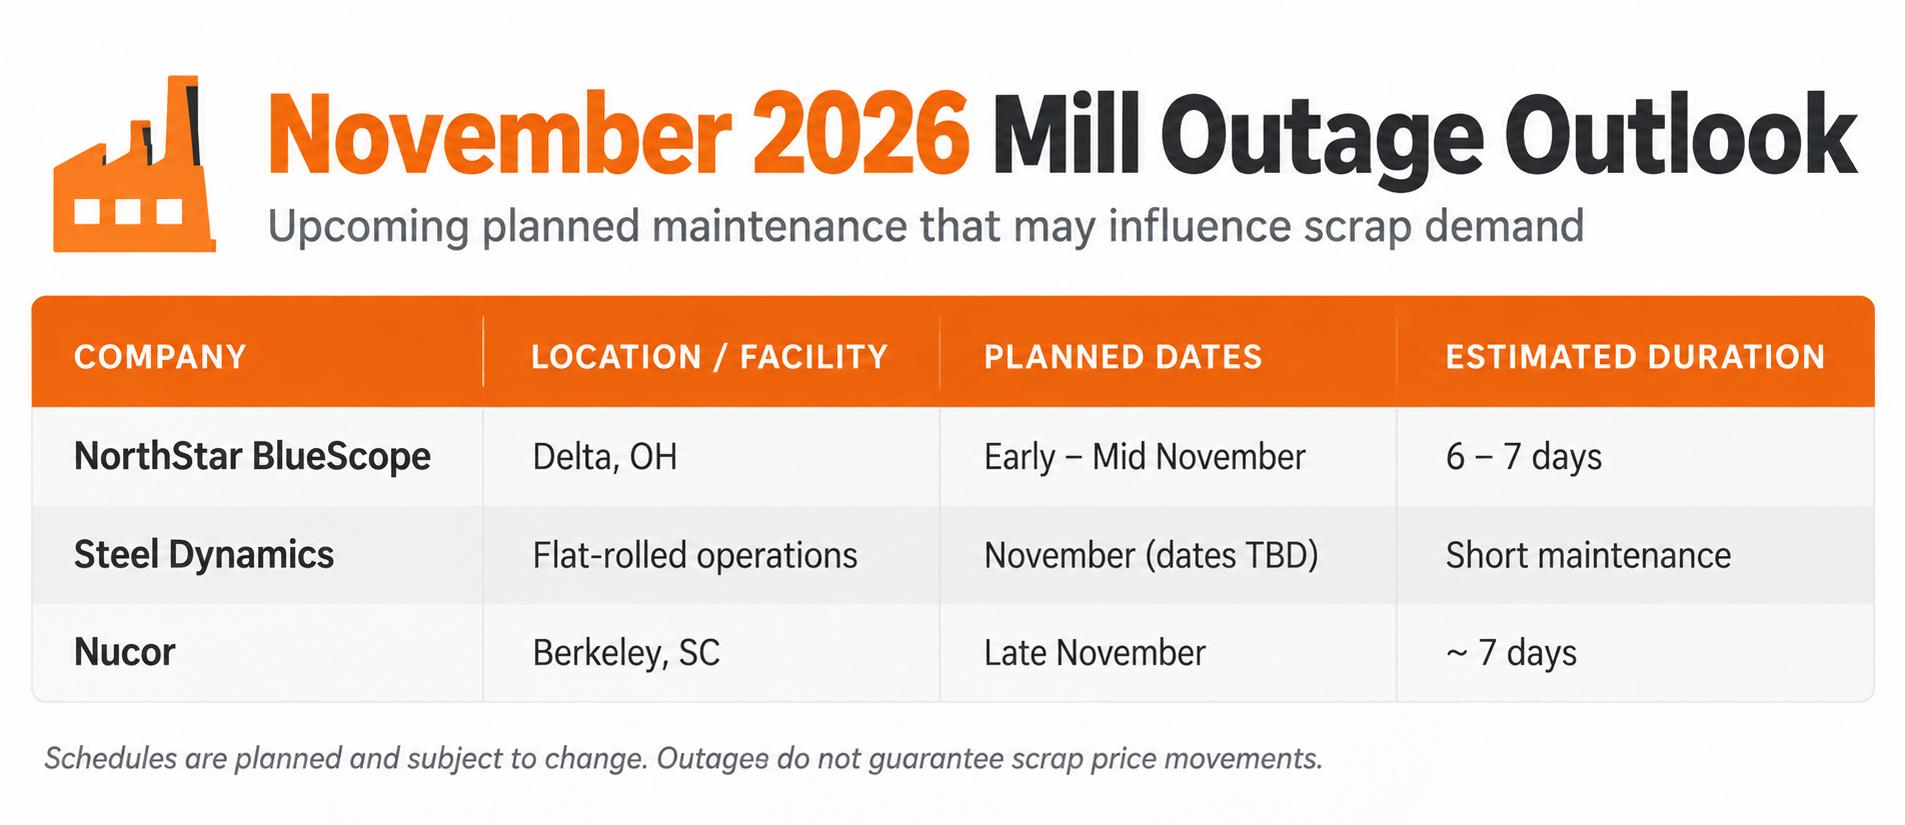
Mill Outages Wind Down – November Demand Could Strengthen
After an active maintenance season throughout September and October, many Midwest steel mills are expected to resume normal production heading into November.
While scheduled outages may have limited some scrap purchasing activity during October, mills returning to production could look to replenish inventories and secure additional material to meet year-end demand.
With mill order books reportedly remaining strong and available scrap supply relatively tight, increased purchasing activity could lead to greater competition for material. These factors may help support another upward movement in pricing as November approaches.
What we are Watching
- Mill Demand – Full order books and the anticipated completion of scheduled maintenance outages should lead to increased scrap purchasing as mills evaluate inventory needs and prepare for year-end production.
- Busheling Futures – Futures are trading above $500/GT suggest a stronger outlook for prime scrap and could indicate expectations for higher pricing heading into the two last months of the year.
- Mill Capacity Utilization – Steel mill capacity utilization is at 80.9% suggests solid demand without straining capacity.
- Tightening Scrap Supply – Slower inbound flows and relatively lean yard inventories may limit available tons. Any increase in mill purchasing could place additional pressure on supply.
- Export Activity – Improving export demand could continue pulling scrap away from the domestic market, potentially tightening supply and supporting pricing.
- Midwest Weather – Colder temperatures and seasonal weather disruptions could begin affecting scrap generation, collection, and transportation as winter approaches.
Bottom Line
Chicago’s November ferrous scrap market is forecast to increase across all grades, building on October’s $30/GT increase.
Strong mill order books, relatively tight scrap supply, and the anticipated completion of scheduled maintenance outages are contributing to a more positive market outlook. With Busheling futures trading above $500/GT and mills capacity utilization rates at 80.9%, conditions could support additional upward pricing pressure heading into November.
How BL Duke Navigates the Market
During the first week of each month—often referred to as “The Buy”—our team works directly with steel mills to secure orders across all ferrous grades. Fastmarkets typically publishes and settles pricing on or before the 10th of the month, which often reflects the outcome of these negotiations. The following weeks are focused on executing and shipping against those commitments.
Market dynamics such as supply and demand, mill outages, export activity, weather conditions, and freight availability all play a role in shaping these negotiations. At BL Duke, we focus on shipping-point pricing and leverage our multi-modal capabilities—truck, rail, and barge—to move material efficiently and maximize value for our customers.
 We will continue to monitor the market closely and update this forecast as new information becomes available leading up to the monthly trade.
Let’s Connect
We’ll work hard to earn your business — and even harder to keep it.