Following an extended delay in October market settlements, the scrap market is starting the fourth quarter strong, with Chicago ferrous prices increasing $30/GT across all grades. For prime scrap, this marks the first upward move since February, following seven consecutive months of sideways pricing.
Tighter scrap supply, improving export activity, higher transportation costs, and healthy Midwest mill demand are supporting higher prices. Meanwhile, non-ferrous markets remain mixed, with copper continuing to show strength, aluminum holding relatively steady, and stainless steel facing softer conditions.
Chicago’s Ferrous Scrap Market
Chicago’s ferrous scrap market is kicking off Q4 with upward momentum after months of relatively stable pricing. Tighter scrap availability, improving export demand, higher fuel costs, and steady Midwest mill order books are all contributing to a firmer market.
Prime Grades. Prime grades, including No. 1 Bundles and No. 1 Busheling, increased $30/GT, marking the first increase since February. Supply remains relatively tight, while strong finished steel pricing and healthy mill demand continue to provide support for prime grades.
Obsolete Grades. Obsolete grades—including Heavy Melt (HMS), Shredded Scrap, and Turnings—increased $30/GT in October, following several months of downward pressure earlier in the year. Lower yard inventories, tighter scrap flows, improving export demand, and stronger competition for available tons helped drive prices higher.
Scheduled mill outages remain an important factor heading through Q4. While reduced buying during maintenance could limit some near-term upside, mills returning to normal production later in the month may need to rebuild inventories ahead of November and winter months.
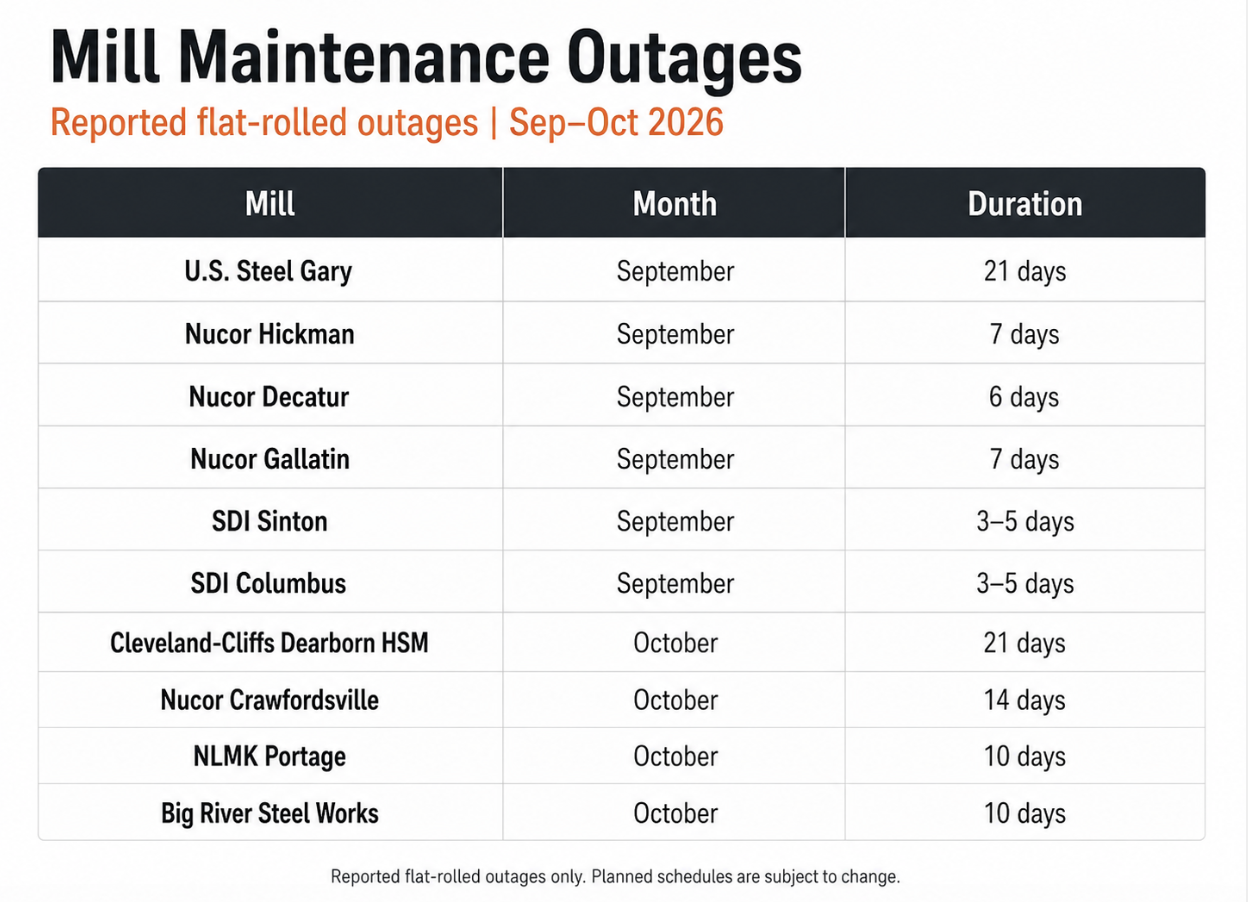
“October is showing the strongest upward momentum we’ve seen in several months. Tighter scrap supply and healthy mill demand are creating a more supportive market as we move into the fourth quarter.”
Chicago’s Non-Ferrous Scrap Market
Aluminum. Aluminum pricing remains relatively stable heading into October. Trade conditions, domestic demand, and North American premiums continue to shape the market, with no major directional shift developing early in the month.
Stainless Steel. Stainless steel has softened, with nickel remaining the primary market to watch. Without a sustained increase in nickel pricing or stronger stainless mill demand, 304 and 316 scrap values may continue to face limited upside in the near term.
Copper. Copper remains one of the stronger non-ferrous markets heading into Q4. Tight global supply and continued demand from infrastructure, electrification, and data center investment are supporting pricing, although the market remains volatile. Copper scrap values are expected to remain well supported as October progresses.
Let’s Connect
We’ll work hard to earn your business — and even harder to keep it.