Chicago’s Ferrous Scrap Market
Chicago’s ferrous scrap market is expected to strengthen in October, with pricing forecast to increase approximately $20/GT across all grades. For prime scrap, this would mark the first price increase since February 2026 after seven consecutive months of flat pricing.
Tightening feedstock, improving export activity, higher fuel costs, and strong mill order books are all adding upward pressure heading into the monthly trade.
Mill Outages Limit October Gains – Q4 Pressure Builds
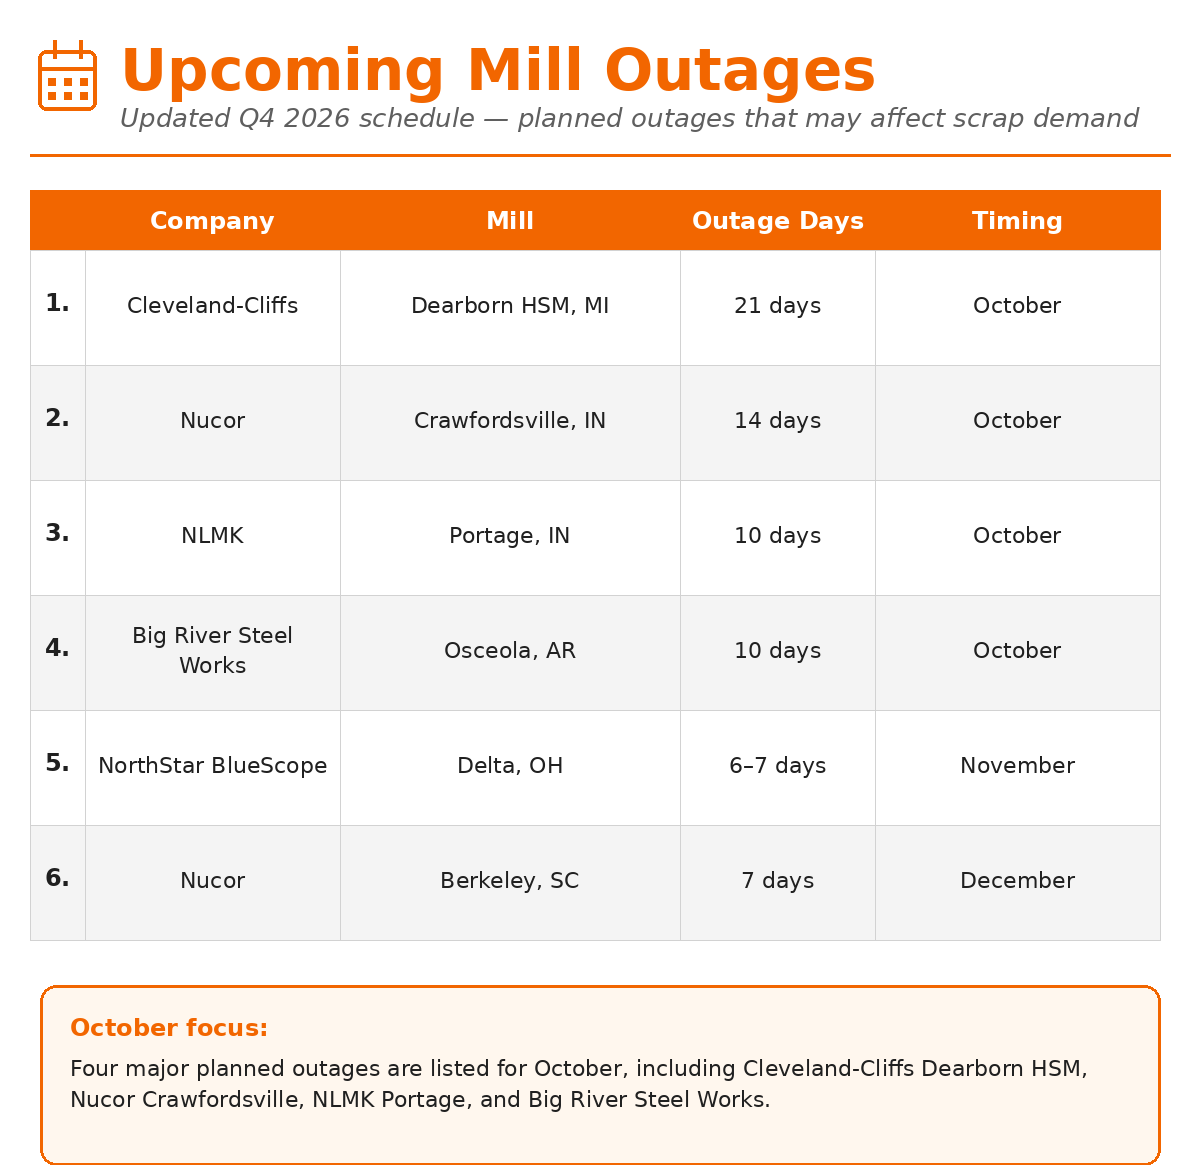
Mill maintenance outages remain one of the biggest factors to watch heading into October, with several major outages scheduled across the Midwest and other key steelmaking regions. This follows six major flat-rolled outages in September totaling approximately 47–51 days of planned downtime.
While tighter scrap supply and steady Midwest demand are supporting the market, reduced mill buying during these outages could limit some of the upside. As mills return to normal production and evaluate their Q4 scrap needs, the market will be watching for additional upward pressure heading into November.
What we are Watching
- Fuel Prices – Diesel and freight costs have moved higher through September, increasing transportation expenses and adding support to shipping-point pricing.
- Export Activity – Export demand has improved, helping pull scrap away from the domestic market and tighten overall supply.
- Midwest Weather – Poor weather could slow scrap generation, collection, and inbound material. With yard inventories already relatively lean, any weather-related disruptions could add further pressure to supply.
- Tightening Scrap Supply – Domestic scrap generation remains tight, particularly for prime grades. Industrial flows have slowed seasonally, leaving many yards with lower inventories heading into “The Buy.”
- Mill Demand – Despite scheduled outages, Q4 mill order books remain healthy. Stronger finished steel pricing could help support continued scrap demand.
Bottom Line
Chicago’s October ferrous scrap market is forecast to increase approximately $20/GT across all grades. For prime scrap, this would be the first increase since February after seven straight months of sideways pricing.
Tight supply, improving export activity, and anticipated Q4 mill demand are supporting a stronger market. Mill outages could limit some of the upside, but overall conditions remain more bullish heading into the fourth quarter.
How BL Duke Navigates the Market

During the first week of each month—often referred to as “The Buy”—our team works directly with steel mills to secure orders across all ferrous grades. Fastmarkets typically publishes and settles pricing on or before the 10th of the month, which often reflects the outcome of these negotiations. The following weeks are focused on executing and shipping against those commitments.
Market dynamics such as supply and demand, mill outages, export activity, weather conditions, and freight availability all play a role in shaping these negotiations. At BL Duke, we focus on shipping-point pricing and leverage our multi-modal capabilities—truck, rail, and barge—to move material efficiently and maximize value for our customers.
 We will continue to monitor the market closely and update this forecast as new information becomes available leading up to the monthly trade.

Let’s Connect
We’ll work hard to earn your business — and even harder to keep it.